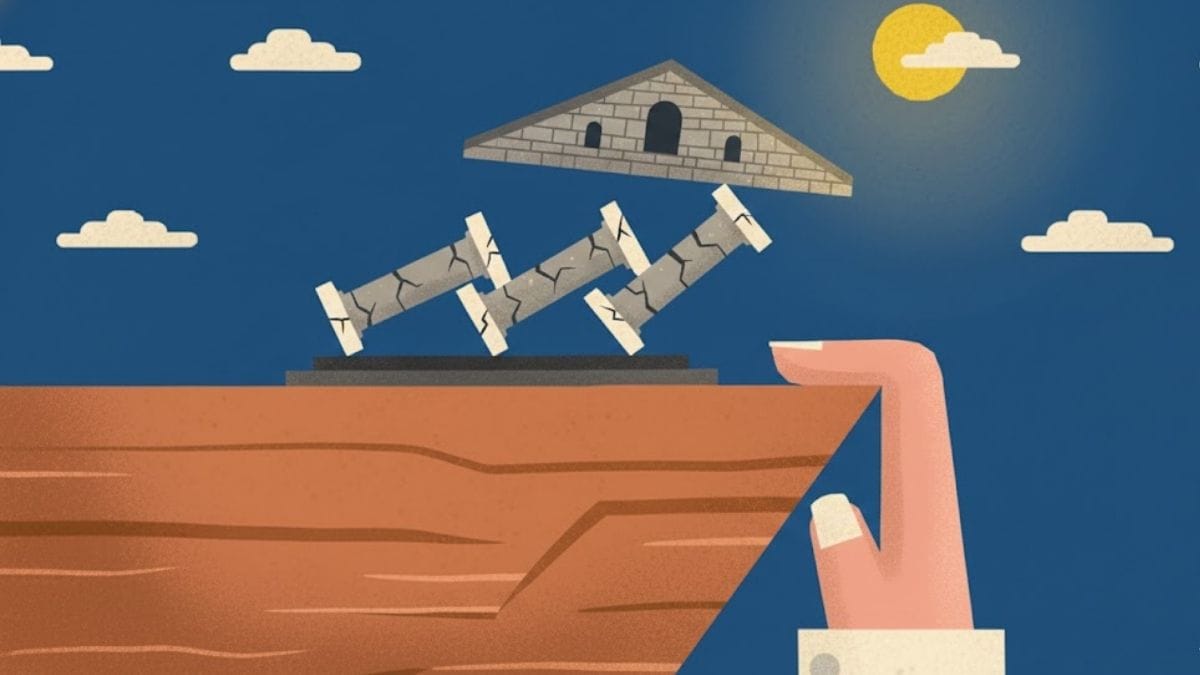
ILLUSTRATION: KATMANDU JOURNAL
WALK INTO any commercial bank in Kathmandu and the marble floors gleam. The ATMs work. The tellers smile. On the surface Nepal’s banking system looks prosperous. Scratch that surface and the cracks appear. Non-performing loans across the 20 commercial banks have reached 5.41% of the total loan book, up from 2.98% just three years ago. Seven banks now surpass the 5% threshold the regulator itself deems risky. At the extreme end, one bank’s NPL ratio touches nearly 8%. Behind these percentages are thousands of unsold apartments, foreclosed factories and frozen collateral: over Rs45bn in non-banking assets that generate nothing but provisioning costs. The banks are sitting on a time bomb. The question is: should the Nepal Rastra Bank (NRB) keep defusing the problem or allow a few weak banks to fail?
The conventional wisdom, embraced by regulators and bankers alike, holds that no bank can be allowed to fail. The governor has said as much. The reasoning is familiar: depositors would panic, credit would seize, the economy would crater. In a country where commercial banks hold 89% of banking assets and the credit-to-GDP ratio stands at 85.8%, the systemic risk is real. So the NRB does what central banks everywhere do: it leans in. It lowers policy rates. It eases provisioning rules. It allows banks with NPLs below 8% to keep borrowing from the central bank. It is now planning a two-stage capital-support programme for big banks facing shortfalls, letting them rebuild buffers gradually rather than forcing them to meet full regulatory standards immediately.
This is the path of least resistance. It is also the path to a more miserable future.
The central bank’s forbearance creates a perverse incentive structure. If poorly managed banks expect bail-outs, why would they improve their underwriting? If loan evergreening—extending fresh credit to troubled borrowers to avoid classification—goes unpunished, why would bankers ever recognise a loss? The IMF has repeatedly raised concerns about this very practice. The NRB’s own inspections have found banks disbursing loans without proper documentation, maintaining interest-rate discrepancies of over two percentage points on similar loans, and manipulating loan records in core banking software. These are symptoms of a system in which consequences have been suspended.
The argument that no bank can fail because the system is too fragile is the argument that keeps the system fragile. Nepal has 20 commercial banks, down from 27 a decade ago, but consolidation has been forced by regulatory fiat rather than market discipline. Mergers have created larger institutions—and, in some cases, larger problems. Banks that swallowed weaker rivals now carry the indigestion of legacy bad loans. Kumari Bank, which swung from a negligible profit to Rs4.17bn largely through merger accounting, still carries an NPL ratio of nearly 7%. Size without soundness is a liability, and not an asset.
What would failure actually look like? Not a run on the entire system. The NRB has a deposit-insurance scheme and the tools for resolution. It has already demonstrated this with Karnali Development Bank, a smaller institution it declared “troubled” and took into management control. A commercial-bank failure would be messier, but mess is what the system needs. It would send a signal: lending to connected but uncreditworthy borrowers carries consequences. It would force the surviving banks to scrutinise cash flows rather than collateral values. It might even unblock the frozen real-estate market by forcing distressed assets to find their true price.
The counterargument—that depositors would lose faith—deserves respect but not deference. Nepal’s banks are awash with liquidity: the deposit-to-GDP ratio stands at 130.7%. The problem is not a shortage of money but a surplus of caution. Banks are sitting on Rs7.19trn in deposits and struggling to lend. A controlled failure, with insured depositors protected and unsecured creditors taking losses, would not drain the system of funds. It would redirect them.
The politics are harder. Nepal has a new government formed after the March elections, and a new NRB governor appointed in May last year. The political class talks a good game about reform. But when the moment comes, the instinct is to protect. Politically appointed board chairs at state-owned banks have resigned en masse, but the bigger problem of political interference in lending decisions remains. Loan defaulters have organised campaigns encouraging borrowers not to repay. Creditor rights are weak; foreclosure takes nearly two years. In this environment, a bank failure would be blamed not on bad management but on the regulator. The governor would face questions in Parliament. The finance minister would wring his hands.
Yet the alternative is worse. Continued forbearance means the NPL ratio, which analysts project could breach 7% by the end of the fiscal year, keeps climbing. Capital buffers, already under pressure at several banks, erode further. Profitability, already squeezed by compressed interest spreads, gives way to provisioning expenses. The banks become zombies—technically solvent, commercially dead, hoarding deposits and refusing to lend. That is stagnation.
The NRB should do what competent central banks do: identify the weakest banks, force them to recognise their losses and resolve them. Some will need to be wound down. Others will need to be merged into stronger institutions on terms that punish existing shareholders. The IMF’s loan-portfolio review of ten major banks, conducted by an external firm, should be published in full. The amendments to the NRB Act should give the central bank the authority to act decisively, not the discretion to delay. Depositors should be protected. Managers should not be.
The banking system is not going to collapse tomorrow. But it is slowly asphyxiating under the weight of bad loans it refuses to acknowledge. The marble floors will stay polished. The ATMs will keep working. And the rot will deepen. A bank failure is a frightening thing. A banking system that cannot fail is a more frightening thing still. Let one fall. The rest might learn to stand. ■