
ILLUSTRATION: ADAM NIKLEWICZ VIA THE ISPOT
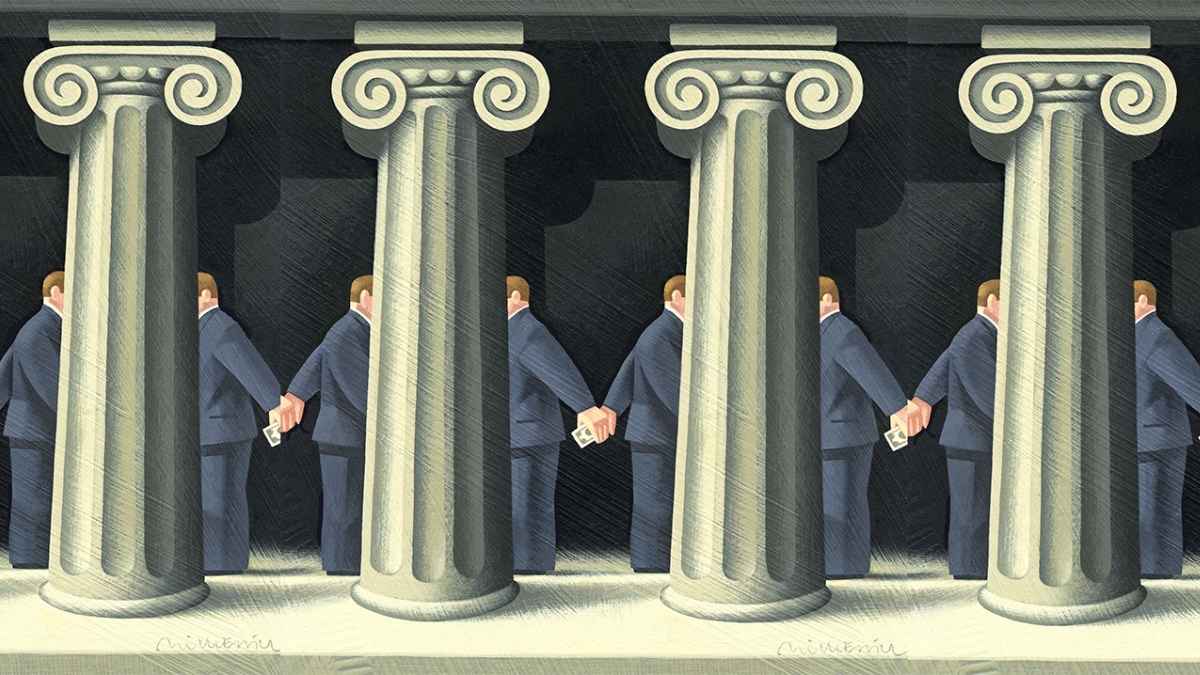
ON APRIL 2nd investigators from Nepal’s Department of Money Laundering Investigation arrested Deepak Bhatta, the chairman of Infinity Holdings, on charges of orchestrating a Rs20bn fraud network connecting several of the country’s most powerful business families to political leaders, bureaucrats and bank executives. Sulav Agrawal, chairman of the Shanker Group’s holding company, was arrested days later. Shekhar Golchha, former president of the Federation of Nepalese Chambers of Commerce and Industry, followed on April 25th. The businesses these men represented—the Shanker Group with Rs125bn in annual turnover, the Golchha Organisation with over a century of trading history, the network of conglomerates that between them shape the price of cement, steel and credit in Nepal—had never faced anything quite like this. The arrests werea criminal matter, as well as a stress test of a business model built for a different era.
Nepal’s family business empires were assembled under conditions that no longer fully apply. The founders worked in a largely protected economy, accessed political relationships as primary competitive tools, relied on informal credit networks and self-assessed regulatory obligations, and kept their books in the family. The first generation of Nepali conglomerate builders—Lunkaran Das Chaudhary and his son Binod, Rawat Lal Agrawal and his descendants, Ram Lal Ji Golchha’s successors, the Bhimsaria family behind Shivam Cement—built structures of remarkable breadth from remarkably slim formal foundations. Binod Chaudhary, now 71 and Nepal’s only Forbes-listed billionaire at $2.1bn, built an empire spanning 202 companies across 32 countries starting from a family shop in Kathmandu. The organisational genius behind that growth was personal rather than institutional.
That model has a ceiling, and Nepal’s most famous conglomerates are approaching it from several directions at once.
The first pressure is succession itself. Binod Chaudhary is transferring CG Corp Global to three sons: Nirvana, who oversees Nepal operations; Rahul, who manages international business; and Varun, appointed global chief executive of CG Foods in May 2025 after the group’s two previous professional CEOs departed within their first few years. CG Foods had planned to list on an Indian stock exchange in 2026; the listing has not materialised. Varun’s mandate—transforming CG Foods from a single-product noodle company into a multi-category food business with a stated turnover target of $19bn—represents an ambition the group has articulated without yet demonstrating the organisational depth to execute. The same trend repeats across the sector: founders who combined the roles of strategist, dealmaker and relationship manager in a single body, handing those roles to children who inherit the assets but not the specific social capital those assets were built on.
The second pressure is transparency. Nepal’s placement on the Financial Action Task Force grey list in February 2025 has introduced, for the first time in the country’s corporate history, a serious external demand for traceable financial flows. The FATF process requires that transactions be documented and disclosed in ways that informal family accounting cannot survive. Nepal’s transfer pricing directive, effective from income year 2024-25, for the first time requires companies with significant cross-border transactions to document the terms on which they deal with related parties. These are not existential threats to any individual business. Cumulatively they are a dismantling of the opacity that made these structures possible.
The third pressure is the exposure that the April arrests created. The investigators found that Jagdamba Steel, one of the Shanker Group’s core companies, had transferred Rs450m into a political fixer’s personal bank account over four days in June 2021. This transfer appeared in no published audit. The Shanker Group, with Rs200bn in bank borrowings, now sits inside an active prosecution with 29 people recommended for charges. The group employs 15,000 people and has obligations across the banking system that the NRB is monitoring. These numbers give the state very little room to be punitive and the group very little room to be defiant. Both sides are trapped in a web of mutual dependency that the founders never intended to build but that the structure of Nepali banking made inevitable.
The fourth, perhaps most underappreciated pressure is competitive. Nepal’s conglomerates built their positions in sectors protected by policy, geography and political access: cement behind high import duties, noodles behind a distribution network that took decades to build, banking behind licensing requirements. Each of those moats is shallower than it was. Cement duties oscillate with smuggling consequences the government cannot control. Wai Wai faces growing competition from Indian instant noodle brands entering through the open border as distribution barriers erode. Banking margins are under pressure from NRB-mandated consolidation that has reduced the number of commercial banks from 28 to around 20 through mergers since 2022. The conditions that made these sectors defensible for family incumbents are not disappearing overnight, but the trend is apparent.
Against these pressures, Nepal’s family conglomerates have two broad options. The first is professionalisation: independent boards, public listings of subsidiaries, separation of ownership from management and the cultivation of executives empowered to make decisions on commercial rather than relationship grounds. The Chaudhary Group’s attempted CG Foods IPO and its hire of professional CEOs before retreating to family management represent the beginning of this path, incomplete and inconsistent.
The second option is continuation: keep the family in control, resist disclosure, use political relationships to manage the regulatory environment and hope that external pressures plateau before they overwhelm. The arrests suggest that the second path is no longer as safe as it appeared.
What Nepal’s family conglomerates have not reckoned with yet is that the first path is a change in the nature of the competitive advantage that built these businesses. The founders competed on access. The next generation will have to compete on execution. Those are different skills. The heirs have inherited empires. They must now prove they can run them. ■




