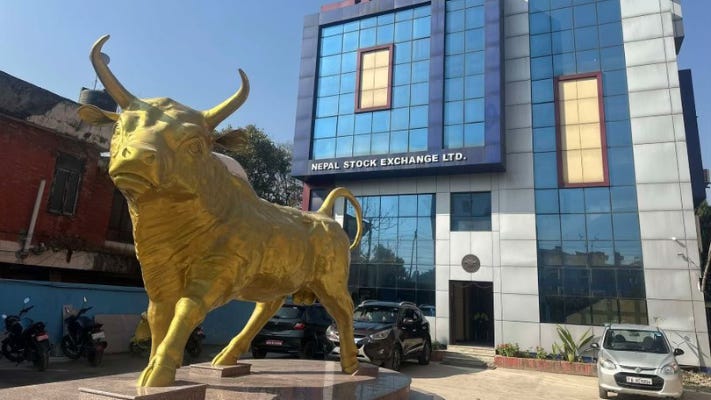
To list or not to list? For most Nepali firms, the question barely arises. The Nepal Stock Exchange (NEPSE), the country’s lone bourse, is home to the usual suspects (banks, insurers, microfinance and hydrocos). Notwithstanding the swelling chorus of investors yearning for diversity, most of Nepal Inc. remains a private affair. That is not because local entrepreneurs are uniquely shy. It is because the incentives to go public are, quite simply, too obscure and the hurdles too obvious.
The stock market is less a barometer of the broader economy than a mirror reflecting regulatory compulsions. Most listed firms are those nudged, or shoved, onto the exchange by sector-specific mandates: banks and insurers must float at least 30% of their shares to comply with licensing rules. Hydropower firms, too, list to fulfil power purchase agreement conditions. The outcome is eight of the top ten firms by market capitalisation are financial institutions. Hydropower, a favoured child of state-backed policy, trails just behind. Other sectors—technology, consumer goods, manufacturing—barely register, like ghost guests at a party they were never invited to.
The chief culprit, ironically, is neither red tape nor tax policy, but simple silence. In a joint survey conducted by the NEPSE and the Milken Institute in 2019, a whopping 84% of unlisted companies confessed that no institution—public or private—had ever tried to explain how or why they might consider listing. That number would be comical were it not so consequential. Of those who had gone public, not one reported having received any awareness or outreach support from the NEPSE. One might expect a stock exchange to market itself with at least the enthusiasm of a new café on Instagram. The NEPSE, apparently, prefers anonymity.
Yet the appetite is there—if only someone would set the table. Roughly 80% of unlisted firms expressed keen interest in seminars or training on going public. When asked how the NEPSE could improve, the top recommendation was not tax breaks, nor legal reform, but marketing. In a country where bureaucrats issue circulars with monastic devotion and regulators favour compliance over communication, this is revolutionary: firms are not demanding favours, just information—if only someone would provide.
That gap in understanding has real consequences. Fewer than half of unlisted firms said they knew the benefits of listing; only a third understood the costs. This fog of uncertainty makes the public market appear needlessly daunting. Listing entails higher compliance burdens: better financial disclosure; stronger governance; and annual scrutiny by shareholders. These are not trivial asks, but they are hardly insurmountable. India’s Bombay Stock Exchange (BSE), for instance, has grown its roster of small and medium enterprises (SMEs) by evangelising, not only by enforcing.
The BSE offers four compelling arguments that the NEPSE would do well to emulate. First, listed firms enjoy access to capital at a lower cost. Second, they can sell equity to fund growth without surrendering control. Third, owners who do list retain big stakes—and influence. And fourth, a public listing boosts prestige, with share prices flashing on tickers and balance sheets attracting more respect in bank boardrooms.
There is precedent. Listed firms report tangible upsides: 60% say access to finance has boosted post-listing; 94% cite enhanced brand visibility; and only 12% feel they lost control of their firms. The problem is not that such benefits do not exist, but that they are not being shouted from the rooftop—nor even whispered from the regulator’s office.
Some structural constraints also merit attention. The three-year lock-up period for foreign private equity investors deters listings as an exit strategy, especially for high-growth firms seeking smart capital. Trimming this to match the one-year lock-up imposed on local early-stage investors would not only create parity. It would signal that the NEPSE is open for global business, too. At a time when domestic entrepreneurs increasingly straddle geographies, this matters.
A deeper pool of listed firms could yield wider benefits. Investors would gain access to more diversified sectors. Firms could tap into equity markets rather than relying solely on debt. The government, perpetually strapped for cash, might see capital markets as an alternative to donor dependency. And the economy as a whole would benefit from greater transparency and corporate governance.The NEPSE, for all its regulatory ambitions, needs to become a storyteller. Listing is not only a compliance box but a growth strategy, a trust signal and a ticket to scale. If the stock exchange wishes to woo more firms into going public, it must shed its monk-like detachment and pick up a megaphone.
In Nepal, as in many places, capital is not just financial. It is reputational. The NEPSE must convince private titans that a listing is not a burden, but a badge. Until then the bourse will still be a cloistered club—not a marketplace.