What do short sellers and gossipmongers have in common? Both profit from bad news. One triggers a market sell-off; the other a family quarrel. Yet only the former is banned in Nepal, notwithstanding conferring a public service.
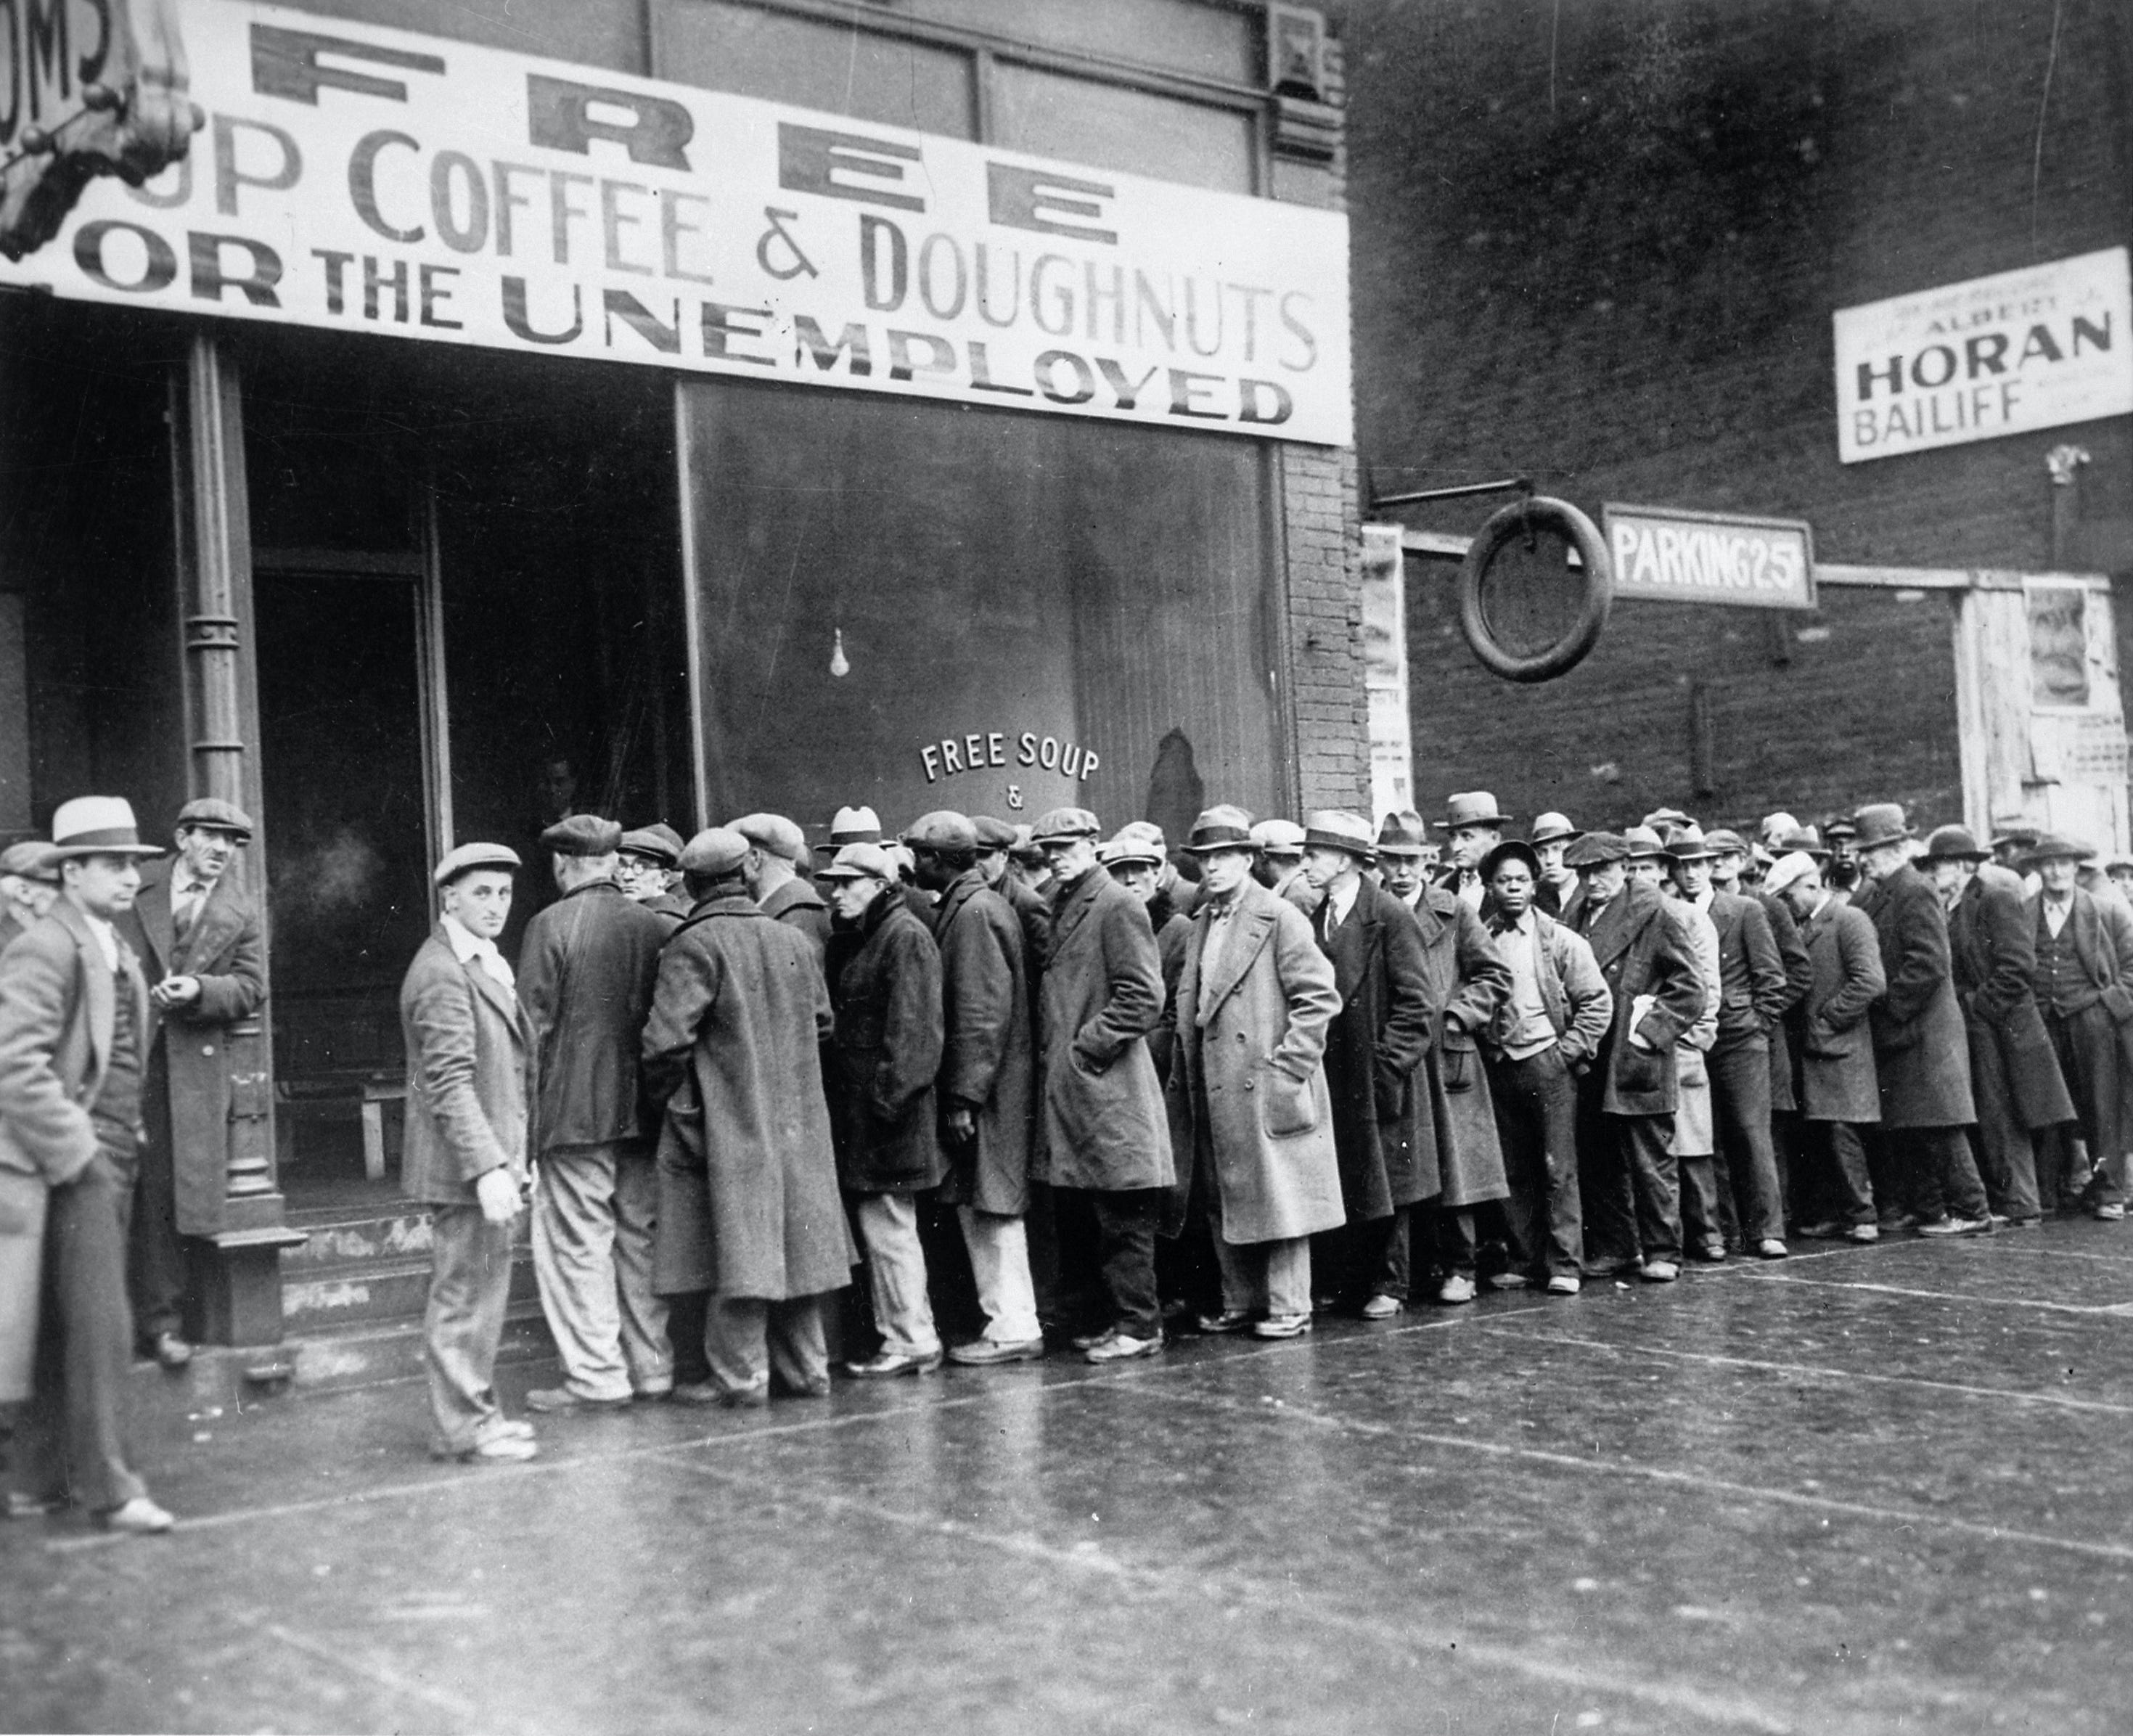
Short-selling, the practice of selling borrowed shares in the hope of buying them back cheaper, has long been a feature of well-functioning markets. It is as old as capitalism itself: the Dutch East India Company was both the world’s first publicly traded firm and the first victim of a short-selling scandal. Its perpetrators, including a former director, were accused of swindling “widows and orphans”—a line of attack that has scarcely evolved over four centuries.
Today short sellers are still the bogeymen of global finance. They were blamed for the crash of 1929, the Asian financial crisis of 1997 and the 2008 meltdown. At various points, regulators from Washington to Kuala Lumpur have tried to muzzle them. The logic is simple: when prices are falling, shoot the messenger. But this impulse is misguided. In reality short-sellers serve a vital, if unglamorous, role: identifying overvalued assets, exposing fraud and instilling discipline in frothy markets.
Nepal, alas, has neither short-sellers nor froth-dispelling discipline. What it does have is a stock exchange dominated by overpriced shares and retail exuberance. The NEPSE index surged to dizzying heights in 2021: with no regard for fundamentals. When gravity finally reasserted itself, the index shed more than 40% in less than a year. But even now valuations are sky-high. Its average price-to-earnings ratio rests above 45—nearly double India’s and almost twice America’s, notwithstanding far dimmer growth prospects.
This is no accident. In the absence of short-selling pessimists are disenfranchised. Investors can bet only on prices rising. This unidirectional market not only misallocates capital, it encourages bubbles, too. As in physics, unchecked pressure eventually causes an explosion.
Legalising short-selling would provide Nepal’s market a safety valve. It would also boost liquidity; sharpen price discovery; and allow for hedging strategies that limit downside risk. These are not theoretical benefits. When short-sellers exposed Enron and Wirecard, they performed due diligence the auditors failed to. Jim Chanos, who famously shorted Enron, once called short-sellers “real-time financial detectives”. Nepal’s stock exchange, where due diligence usually begins and ends with hearsay, could use a few such sleuths.
Sceptics cite the dangers. Short-selling, they argue, is risky and unfair. Risky it certainly is: losses are theoretically unlimited since a stock can rise infinitely. Going long on a dud merely loses your stake; shorting a market darling can bankrupt you. The GameStop saga of 2021 is a case in point. Melvin Capital, a hedge fund betting against the video-game retailer, lost billions as retail investors drove up the price in a Reddit-fuelled frenzy. But such episodes are rare—and say more about exuberant mobs than malign short-sellers.
Nor is short-selling the preserve of the plutocratic elite. While institutional players dominate in most countries, retail investors are not excluded. Nepal already has a margin-lending infrastructure. Extending it to enable shorting would not require reinvention. Just regulation. Brokers could lend stocks, just as they lend money. The mechanics are simple; the obstacle is mindset.
One sector where shorting could bring clarity is hydropower (among others), the most fashionable investment theme. Dozens of companies, many with no revenue and scant capacity, command valuations befitting green energy giants. Investors are promised Everest returns. Short-sellers would ask awkward questions—and perhaps deter speculative surges boosted by press releases rather than performance.
Critics may still be unmoved. The idea of profiting from plunge feels unpatriotic. In a collectivist society, betting against one’s own economy—or neighbour’s shares—can be seen as sabotage. But markets are not temples. They are machines for allocating capital. When prices lie, money is wasted.
Introducing short-selling in this country will not eliminate irrational exuberance. It will not prevent all crashes or cure all mispricing. But it will introduce a dose of scepticism, which markets—like democracies—desperately need.
After all, when everyone thinks alike, no one thinks very much. ■