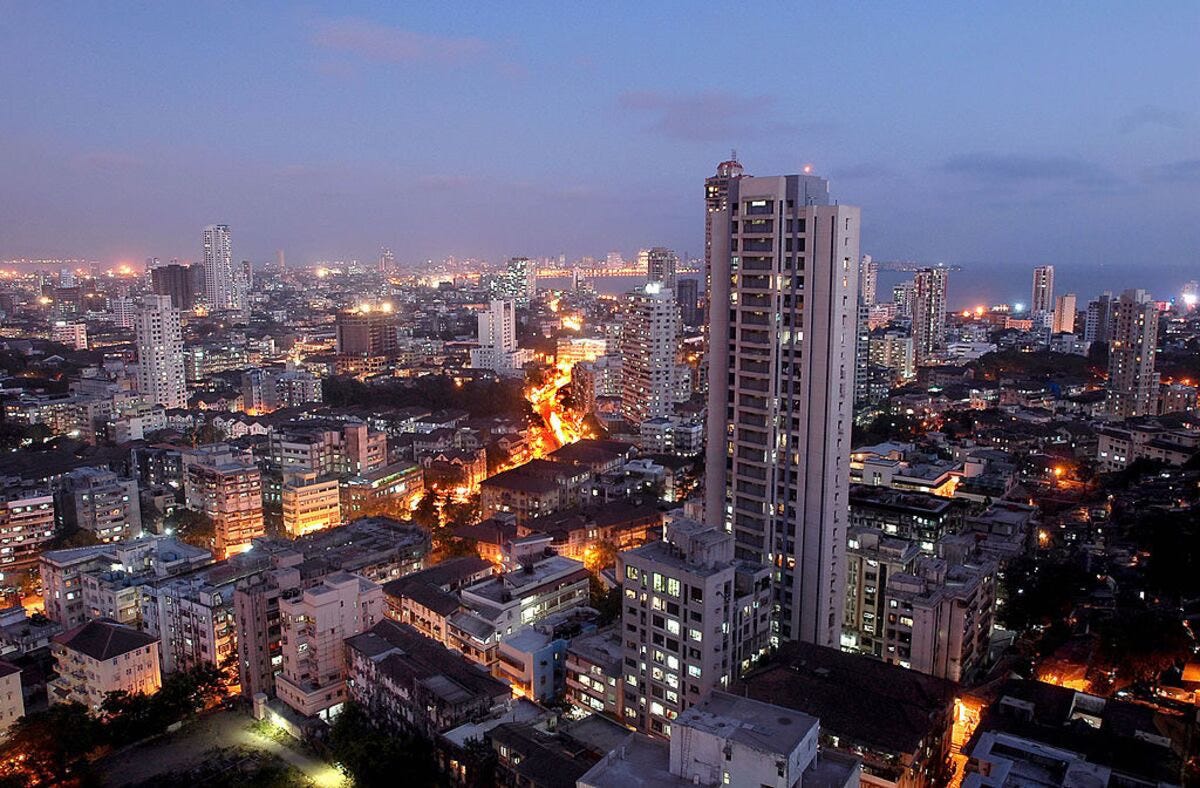
Photographer: Abhijit Bhatlekar/Bloomberg
Once the preserve of zamindars and Bollywood stars, wealth in India is becoming boringly common. By 2027 Goldman Sachs predicts the country will boast 100 million affluent individuals—people earning roughly $10,000 or more a year. Though that figure is modest by Western standards, it buys considerable clout in Mumbai or Bangalore. This cohort, up from around 60 million in 2023, is reshaping everything from consumption to politics.
In a country where half the population still survives on less than $3.65 a day, the notion of “affluence” is necessarily elastic. Goldman’s analysts define it by action rather than aspiration: those who take at least one flight a year, order food online monthly, hold postpaid phone plans or credit cards and file tax returns on incomes surpassing 1 million rupees ($11,672). That behavioural definition tallies, they estimate, with a slice of about 4–7% of India’s population, modest in relative terms but larger than Germany in absolute ones.
This group is growing quickly. From 2019 to 2023 it expanded at an annual clip of 12–13%, outpacing GDP. Its tastes have transformed consumer markets. In sector after sector—from automobiles to alcohol—firms focused on premium buyers have outperformed mass-market rivals. SUV sales race ahead while hatchbacks sputter. Premium whiskies flow more freely than economy blends. Even in healthcare and horology (watches, to the uninitiated), the upscale are proving to be better business.
There is more at work there than just income growth. India’s wealth effect, turbocharged by rising stock ownership and post-pandemic euphoria, is helping convert paper gains into real-world exuberance. Before covid-19, some 41 million Indians held online trading accounts; now that number outstrips 100 million. Much of the windfall has accrued to those already atop the pyramid. A government survey suggests 90% of India’s privately held gold—the country’s favoured store of wealth—is owned by the top decile of earners.
That would be less stunning if the rest were catching up. But India’s much-vaunted demographic dividend is producing an economy with both a gleaming glass roof and a fraying floor. Consumption among lower-income groups has slowed, most so in rural areas. Fast-moving consumer goods—shampoos, snacks, soaps—are no longer selling as briskly in village shops. Agricultural prices have stagnated while inflation has disproportionately pinched poorer households, which lack savings to cushion the blow. Successive shocks—demonetisation, a sweeping goods and services tax and pandemic lockdowns—have battered small businesses and informal workers. The fallout is an India that is converging with the global middle class at the top while diverging from it below.
Some policymakers see a silver lining: a large and surging upper-middle class provides a stable tax base and a ready market for domestic champions. It can underpin public finances and anchor urban demand. But a widening chasm between aspirational elites and the rest also carries risks. In a democracy with 900 million voters, 100 million affluents are still a minority. Their tastes may shape stock indices but their preferences do not always fall in line with those of the less fortunate, something political parties are unlikely to forget.
There are cultural implications, too. India’s economic story is often told in aggregate: $5 trillion GDP targets, smartphone penetration, digital payments. But it is lived in fragments. The metro-dwelling executive who orders truffle fries via app lives in a different economy from the sugarcane farmer awaiting minimum support prices. The Indian dream, once collective, is becoming stratified. The old middle-class ethos of thrift and modesty is being replaced by an aesthetic of ambition: credit cards, curated holidays, luxury brands and stock portfolios.
That might not be all bad. The affluent spend, invest and—eventually—vote. Their emergence could catalyse reforms in financial markets, consumer protection, public services, among others. But should India’s economic ladder become more like an escalator with a VIP lounge at the top and a jammed bottom rung, social friction could follow. A society where 100 million live like it’s 2030 while the rest subsist in 1995 risks more than envy: it risks political volatility and economic underperformance.
Still, the affluent class is likely to keep expanding. The wealth effect lags but compounds. People spend more not when their stocks rise once but when they rise for three years running. If growth holds the 100-million mark will be passed by 2027, and perhaps well exceeded. By then India may be exporting not only coders and CEOs but also the contours of a new global middle class: digitally native, financially literate and increasingly difficult to ignore. ■