
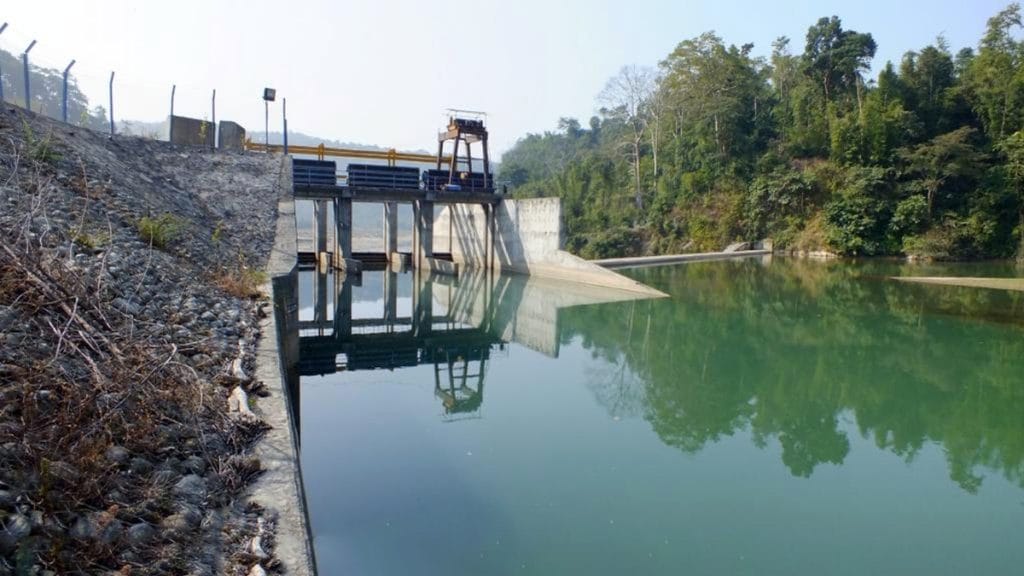
Photo: Sanima Mai
Hydropower is sold as Nepal’s economic ace. The country’s rivers tumble down Himalayan cliffs with a velocity that seems to invite monetisation. Politicians, donors and stockbrokers alike speak of kilowatts with reverence. Yet amidst the babble of IPOs and commissioning announcements, the hydropower index on the Nepal Stock Exchange is doing something peculiar: it is going downhill.
In the last 12 months the hydropower sub-index has tanked by 11.1%, even as the broader market has leapt by over 24%. Trading volumes remain high: over NPR 654 crore worth of hydropower shares changed hands on July 17th alone, suggesting something closer to manic speculation. On the face of it these firms ought to be darlings of the investing public. Power demand is swelling; generation capacity is expanding; and regional export opportunities are multiplying. The numbers, though, are less than bullish
The average price-to-earnings ratio for hydropower stocks is a baffling 88.85, more than four times the banking sector’s 18.93. A high PE ratio can reflect bullish growth expectations, but in this case it hints at thin or vanishing profits. Several listed firms are haemorrhaging cash. Balephi Hydropower, for example, reports a negative earnings-per-share figure of NPR -11.91 and an equity return of -16%. Its margins are negative to the tune of 60%. Another laggard, Asian Hydropower, is in even worse shape, with a PE of zero (due to negative earnings) and a return on equity of -14%.
Amongst the better performers, some show genuine promise. Mountain Energy Nepal (MEN) boasts an EPS of 23.82 and an ROE of 16%, with a respectable 50% year on year profit growth in the third quarter. Yet even MEN trades at a frothy PE of 46.8, evidence investors are paying a steep premium for the relative rarity of profitability. Others, such as Arun Valley Hydropower Development and Api Power, have posted bumper growth numbers—5800% and 689% respectively—but their valuation multiples remain disconcertingly high, indicating sentiment is doing more lifting than cash flows.
This is not unique to hydropower but the stakes are higher here. Investors see the sector as a patriotic bet: an asset class wrapped in the national flag. This has created a powerful narrative, though a fragile one. High book-value multiples (the sector average PB ratio is 4.67) suggest market prices bear little relation to the underlying assets. That might be tolerable for a software firm whose true value lies in code and brand equity. It is more difficult to justify for power plants that depend on rainfall, licensing agreements and fragile grid infrastructure.
The dissonance transcends accounting metrics. Most hydropower companies are small, under-capitalised and dependent on project finance. Construction delays and environmental troubles, among others, frequently derail even well-managed firms. Once a plant begins generation, the returns tend to stabilise but it can take years—sometimes decades—to reach that stage. During this gestation period, stocks trade largely on promise and persuasion.
Retail investors in particular appear enamoured with these promises. Hydropower IPOs are frequently oversubscribed. Social media is awash with tips and rumours. The NEPSE’s bulletin boards read like fevered forums. Yet many buyers fail to scrutinise income statements or question the sustainability of explosive growth numbers. As a result poor performers continue to attract bids while good ones get burdened with unrealistic expectations.
Government policy adds to the muddle. The state guarantees power purchase agreements for many private-sector hydropower firms, often at fixed rates for years. Though this reduces market risk, it also embeds price rigidity. Export agreements with India and Bangladesh are hailed as breakthroughs but transmission infrastructure remains patchy and bureaucratic bottlenecks persistent. A surplus of supply during the monsoon contrasts sharply with dry-season deficits, further muddying revenue projections.
Meanwhile the regulatory environment provides few safeguards. The NEPSE’s disclosure requirements are erratic, and financial reporting standards vary wildly. Key metrics like cash flows are missing for several companies. Some firms report figures that defy plausibility. One company, BGWT, posted a 33% fall in profits but still trades at a PE of 139, more an act of faith than financial reasoning.
The broader context is equally sobering. The economy is recovering, and remittance-fuelled liquidity has boosted asset prices across the board. Yet such tailwinds cannot rescue structurally weak firms. If the capital market is to finance development effectively, they must separate story stocks from sound ones. Hydropower may be a national strength but it is no shield against bad governance or speculative mania.
Investors would do well to look beyond surface-level optimism. Projects with consistently positive margins, credible management and reasonable valuation multiples deserve attention. The rest belong in a cautionary tale about how dreams of abundance can degenerate into bubbles.
The rivers may flow swiftly, but capital, if misdirected, can sink without a ripple. ■





