NEPAL HAS A problem any emerging economy might envy, and is doing its best to waste it. Sitting at the heart of its financial system are three colossal pension funds, with combined assets of over $5bn. They have a deep pool of long-term capital that could help build the roads, power grids and businesses the country desperately needs. Instead they behave like the most timid of savers. Such caution is a form of self-sabotage for a poor country with big ambitions.
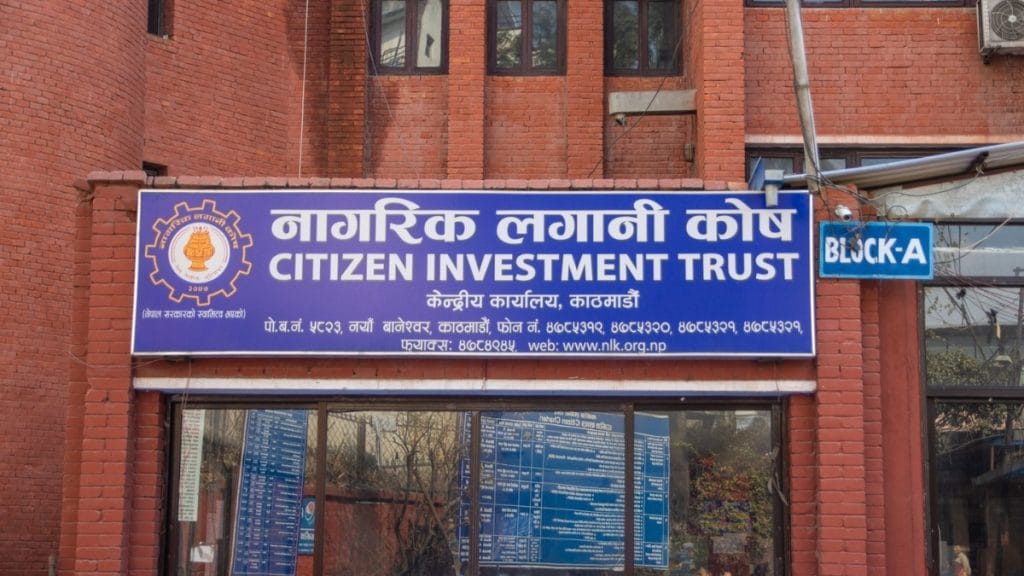
The sums required are vast. Official estimates suggest meeting Nepal’s development goals by 2030 will need annual investment worth about 7% of today’s GDP. The state cannot pay that bill alone. The private sector is meant to chip in a third, but domestic capital markets are feeble. Banks are overexposed to property and hydropower. The stock exchange is a casino. The only serious institutional money therefore lies with the pension funds—the Employees Provident Fund (EPF), the Citizen Investment Trust and the Social Security Fund (SSF). And they are not playing their part.
Notwithstanding their heft, these institutions invest as if the modern economy does not exist. Their portfolios are clogged with government debt and bank deposits. Less than a twentieth of their assets touch private equity, venture capital or anything resembling a growth company. The SSF issues press releases boasting of placing millions in fixed deposits, as if this were a mark of genius. This timidity is understandable, up to a point. Nepal’s politics are volatile, its policies unpredictable. And its corporate governance is opaque. Preserving capital feels safer than chasing returns.
But the cost of that is mounting. Whereas local funds cling to paltry yields, foreign investors are snatching up the opportunities. International development banks are financing funds that back everything from solar power and startups to medical clinics. In essence outsiders are capturing the upside of Nepal’s growth while its own nest eggs gather dust. The result is a stunted market. Promising firms cannot find local capital to expand. Private-equity funds are tiny and have no easy way to cash out. Liquidity is a myth.
This state of affairs is increasingly seen as untenable elsewhere. Britain’s new Labour government, for instance, wants to push pension money into domestic private assets, lamenting that foreign funds tend to outbid local ones for British projects. If outsiders believe in your economy more than your own institutions do, it is a national embarrassment. Nepal suffers the same embarrassment, without the accompanying debate.
The funds themselves are not villains. They are cautious stewards in a murky environment. But their mandates are narrow, their boards risk-averse and, worse, their governance outdated. The polite strategy of issuing guidance and hoping for change has failed. It is time for a nudge with teeth. The government should mandate that a small share of these funds’ assets—say, 5-10%—be allocated to private markets. To mitigate risk, this could be channelled through accredited “funds-of-funds” targeting specific sectors like climate technology or digital infrastructure.
Sceptics will cry that this violates the funds’ duty to protect savers. That confuses prudence with paralysis. A fiduciary’s job is to seek sustainable long-term returns rather than avoiding any whiff of volatility. Pension funds from Canada to Australia plough more than a fifth of their money into private equity and infrastructure. Even Kenya and Vietnam are building frameworks to allow it. Nepal is still debating whether such asset classes are too exotic to touch. Fear of novelty is a luxury it cannot afford.
Of course, a mandate alone is not enough. Regulators must create clear rules for private investments. The government must help structure bankable projects in infrastructure. Pension boards need independent experts with relevant experience. And the stock exchange needs an overhaul to give investors a viable exit. None of this is simple but the alternative is worse.
The danger is financial as well as generational. Today’s workers are tomorrow’s pensioners. Their future payouts depend on their savings being put to work today. Left idle in low-yielding deposits, these vast funds will be eaten by inflation and left behind by a changing economy. They are tools for transformation, currently trapped in a culture of caution posing as wisdom. It is time to give them a firm push. ■
Correction (July 21st 2025): A previous version of this article misstated the annual investment needed to meet Nepal’s development goals as a share of GDP. This has been corrected. Sorry.