Image VIA X
SIXTY-TWO INTERNET service providers are chasing a finite number of subscribers in Nepal. That is roughly one ISP for every 250,000 people, a ratio that would raise eyebrows in any market. In a country where half the population remains offline, it suggests a curious mismatch between entrepreneurial zeal and commercial reality. The race to push megabits per second has become a contest over who can survive selling them cheaply. The business of bandwidth, once lucrative, is approaching a phase of maturity that promises pain for balance sheets.
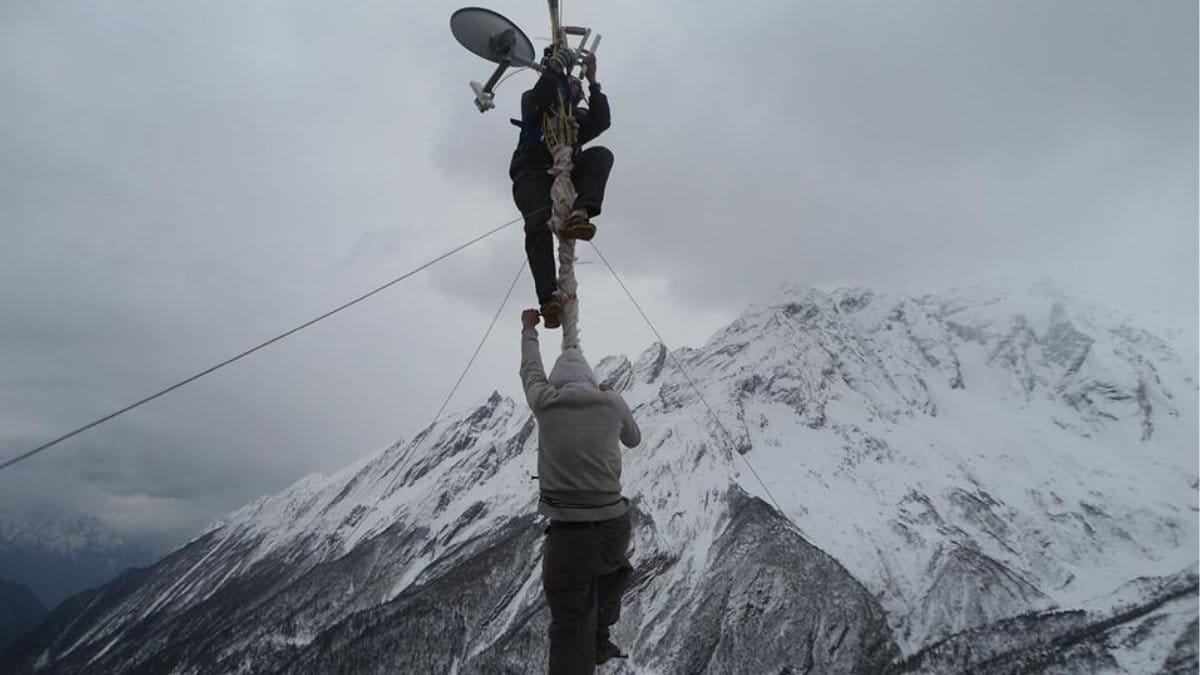
Growth still exists, though barely. As of early 2024 around 15.4m Nepalis were online, according to Kepios, a research firm. Yet only one in five of those users relies on fixed broadband. The rest make do with mobile data or nothing at all. Topography explains part of the gap. Unreliable electricity and uneven household incomes explain the rest. Laying fibre across the Himalayas costs money. Convincing a household in a rural district to pay for it costs more.
The problem is not supply. Between 2017 and 2024 the number of ISP licences issued by the regulator more than doubled, from under 50 to over 100. Many of the licensed firms are dormant. Those that are active compete in conditions more congested than Kathmandu’s ring road at rush hour. CG Net, a unit of the Chaudhary Group, fired the opening salvo in 2021 by offering 120 Mbps packages at Rs999 ($7.50) a month—twice the speed and half the going rate. Bigger incumbents, led by WorldLink and Vianet, which holds around 8% of the market, responded with haste. WorldLink’s Photon series now boasts packages of up to 600 Mbps.
The escalation was easy to predict. Speed is both a marketing pitch and a technical benchmark. Raising it costs relatively little for firms with fibre assets and access to international gateways. But subscriber growth is slowing, and capacity is plentiful. The next battlefield is price. Here Nepal looks vulnerable. The International Telecommunication Union advises that broadband costs in developing economies should not cross 2% of average annual income. Nepal’s ratio hovers around 2.6%, compared with under 1% in India, Pakistan and Sri Lanka. A megabit in Mustang costs more to supply than a megabit in Mumbai. That is not a recipe for fat margins.
Policy may ease the strain, though it is no cure. In 2021 the Nepal Telecommunications Authority introduced rules mandating infrastructure sharing between ISPs and telecoms operators. Towers, ducts and poles may now be co-used, cutting duplication and nudging expansion into underserved areas. Whether the savings lower prices or merely shore up margins is unclear. The answer probably depends on how fiercely the remaining players compete. Urban markets are saturated, so attention is shifting outward. WorldLink has expanded aggressively into provincial towns and villages, offering discounted plans and claiming over 1m subscribers. Smaller rural providers are ceding ground to a well-financed giant with pricing power.
Average revenue per user is sliding. Promotional deals and discount wars, especially in the Kathmandu Valley, are eroding unit economics. That pattern is familiar to anyone who has watched telecom markets elsewhere. Early phases reward speed as a sign of modernity. Later ones mean price cuts as proof of survival. Nepal is crossing that line. Unless firms diversify into new products, margin compression will continue. A few try to differentiate through customer service or niche offerings. Most struggle. Selling raw bandwidth is no longer enough. Value-added services—content bundles, enterprise packages, cloud solutions—are emerging as lifelines.
Consolidation beckons. Smaller firms squeezed by capital requirements will disappear or be absorbed. Bigger players will exploit economies of scale, but even they face a ceiling. The average revenue per user in Nepal’s fixed broadband market is among the lowest in South Asia. That is good for households. It is terrible for shareholders. One executive at a mid-sized ISP, speaking on condition of anonymity, put it bluntly: “We are selling a luxury product at utility prices.”
Consumers may gain in the short run. Prices will fall further. Service quality, however, will depend on how well providers reallocate capital from marketing to maintenance and from cities to hinterlands. Speed matters. Reliability matters more. The winners will be firms with deep pockets, broad networks and the creativity to turn bandwidth into something more than a commodity. That prize remains elusive. Nepal’s rush to wire itself may end with many providers unplugging their own ambitions. ■