
IMAGE: SHIVAM
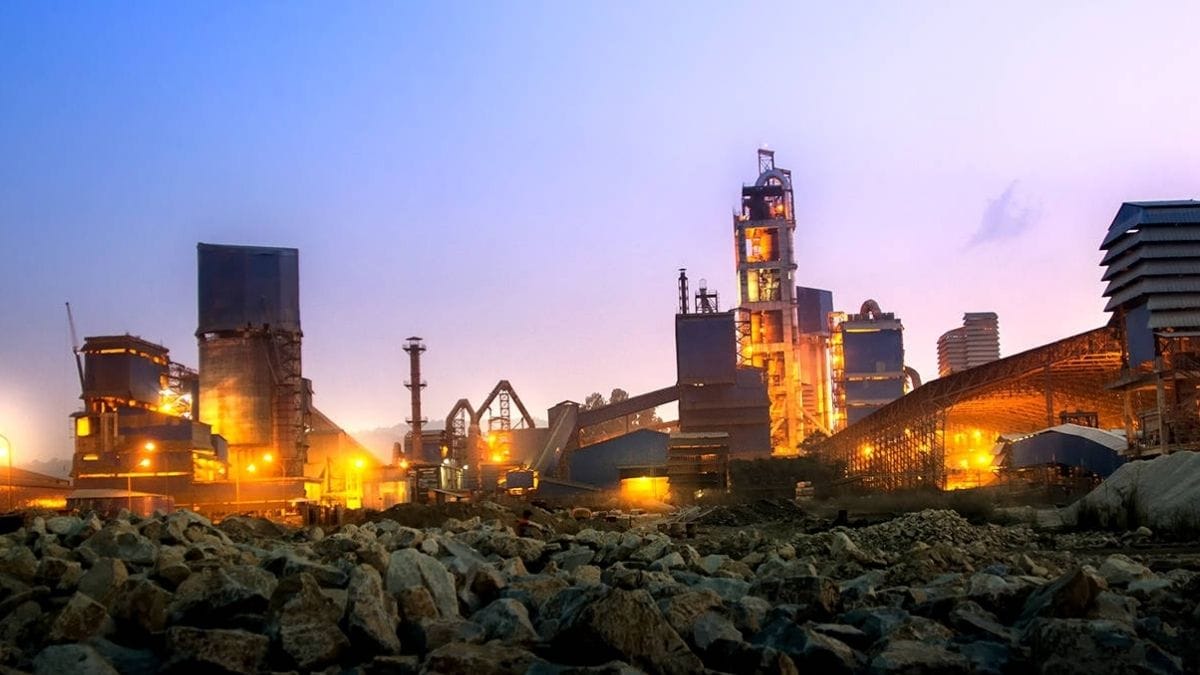
ON THE banks of the Trishuli river, 70km from Kathmandu, a transformation is under way. Chinese and Nepali engineers are carving tunnels through Himalayan rock to house turbines that will generate 216 megawatts of electricity. The project is one of dozens scattered across the hills, evidence of a rare and real private-investment boom.
In the 18 months to January, bank lending to the electricity sector—almost all of it for hydropower—surged by 26%, to Rs463bn ($3.17bn). The private sector has spotted an opportunity that makes sense: reliable power-purchase agreements, new transmission lines and the promise of export revenue from India. It has responded with sustained capital commitment. This, economists mutter into their morning coffee, is what development looks like.
That success, however, obscures a more troubling picture elsewhere in the economy. The central bank’s credit data, released in February, offer the most granular view available of where private investment is actually happening—and where it is conspicuously not. A few sectors hum with activity. The rest are either stagnating or retreating. The fastest-growing category of lending, meanwhile, has nothing to do with investment at all.
Heavy construction, which includes highways and bridges, saw credit rise by nearly 40% over the same period, to Rs145bn. That sounds encouraging. But much of this is private firms building on public contracts, which means their fortunes depend on government capital spending—and that has been declining.
Some of the growth in construction lending may merely reflect contractors loading up on credit while they wait for the state to pay its bills. Manufacturing credit expanded by a more modest 12.7%, to Rs923bn, with decent growth in food processing and basic metals.
Yet bankers and industrialists alike caution that much of that is working capital—money to keep factories running not to build new ones or buy new machinery. The credit categories most directly linked to expanding productive capacity are flat or falling. Lending for agricultural machinery dropped by 10%; for office and computing equipment, by 16%. Firms are not placing big bets on the future.
The sector where Nepal most needs such bets is agriculture. More than 60% of the population depends on it, and productivity is wretched. Yet agricultural credit actually fell over the 18-month period, by 1.3%. The retreat is even starker in subsidised lending schemes meant to encourage farming and entrepreneurship. Loans for women entrepreneurs dropped by two-thirds; commercial agriculture loans fell by 38%. The signal could not be clearer: the formal financial system is pulling back from the rural economy. The consequence is not just slower growth but a hardening of the subsistence trap that keeps millions of Nepalis poor.
What then is growing? Categories that have little to do with factories, fields or power stations. Gold and silver loans—households borrowing against their jewellery and bullion—surged by 66%, to Rs101bn. Loans classified as “consumable” rose by 24%, to Rs1.26trn. Margin lending, used to buy shares, jumped by 35%. The banking system is channelling credit toward consumption, financial speculation and collateral-backed personal lending. This is money that supports spending in the short term but does nothing to build the economy’s capacity to produce more in the future.
That pattern is consistent with what the national accounts show. Domestic savings are low, down to 6.6% of GDP from 15.3% in 2019. Investment as a share of GDP is stuck. But consumption holds up, buoyed by remittances from the millions of Nepalis working abroad. The banks, for their part, prefer to lend against easy collateral—gold, shares, land—rather than take on the risk of project finance. Why underwrite a new factory when you can lend against a gold necklace and sleep soundly? The result is a paradox: an economy awash with liquidity, much of it from remittance inflows, that is not translating into productive investment. The banks are intermediaries, but they are intermediating consumption not capital formation.
None of this means hydropower is a mirage. The electricity sector’s growth is real and will deliver returns for decades. Heavy construction may yet pick up if the government sorts out its payment arrears. Manufacturing could surprise. But the overall picture is one of an economy that is eating its seed corn. Credit is flowing but it is circling in the shallows—financing purchases of gold, shares and consumer goods—rather than ploughing into the deep water where new capacity is built. Nepal’s private sector will build dams. It is far less clear that it will build much else. ■





