ILLUSTRATION: SEBASTIEN THIBAULT
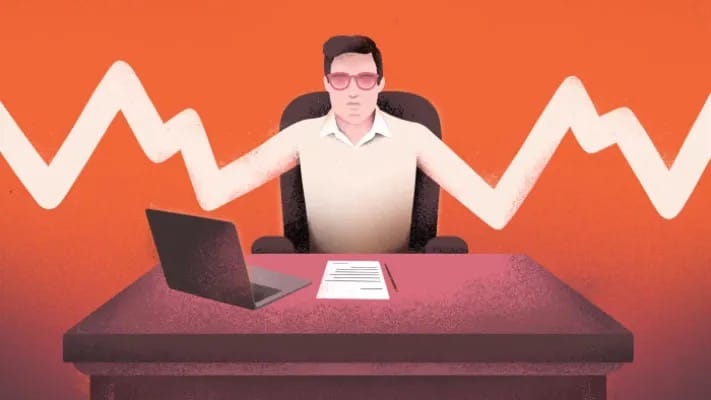
Nepal’s stock market appears to believe in levitation. Valuations float upward with breathless enthusiasm, altering little in the real economy, only to descend just as swiftly in the absence of provocation. A pattern has emerged. Volatility is not an aberration: it is the operating principle.
Markets misbehave everywhere, but few do so with the erratic flair of NEPSE. Researchers have attempted to capture this capriciousness in formal terms. Their verdict is unsurprising: NEPSE is not only volatile, it is also among the most unhinged exchanges in the world. Investors in Kathmandu, who monitor share prices as one might track monsoon clouds—warily and with limited confidence—will find academic confirmation for their instincts.
The index’s peculiar dynamics arise from an uncomfortable truth. Most trading is not anchored in information. Instead it is driven by sentiment, hearsay plus momentum. This explains why returns skew disproportionately to the right. Unlike most equity markets, where bad news travels faster than good and drags prices down with brute force, NEPSE exhibits the opposite pattern: big positive returns are more frequent than big negative ones. Optimism, it seems, is over-supplied, and pessimism underpriced.
That asymmetry is difficult to reconcile with classical finance theory. Conventional explanations—such as the leverage effect, which posits firms with high debt ratios should see asymmetric volatility, or the feedback effect, which assumes falling prices induce more fear than rising ones induce greed—find little empirical support here. Instead behavioural finance offers a more plausible lens. The dominant trading ethos resembles that of retail-driven penny stocks: exuberance, amplified by the fear of being left behind.
Another anomaly is returns exhibit autocorrelation. Gains tend to beget more gains; losses cluster too. This pattern violates the efficient-market hypothesis, which insists prices should follow a random walk, devoid of memory. In NEPSE’s case, the walk appears to be more of a stagger. Prices are sticky, not in the Keynesian sense, but in their insistence on following prevailing winds rather than fundamentals.
The lack of correlation with global markets deepens the puzzle. Given its proximity to India, Nepal’s index might be expected to track movements in Mumbai. It does not. In fact the relationship is mildly negative. The disconnect from Western markets is even more pronounced. This is less a case of decoupling than disconnection. Poor investor protections, weak disclosure norms and an ineffectual regulatory regime combine to sever NEPSE from broader currents. What happens on Wall Street or Dalal Street seems to matter about as much as weather patterns in Oslo.
Manipulative practices thrive in this vacuum. Pump-and-dump schemes, front-running, coordinated speculation are operational features. Regulatory capacity is thin, constrained by limited surveillance tools and outdated statutes. As a result share prices respond less to earnings forecasts and more to rumours, social media posts and the whisper networks of brokerage houses.
The implications are grave. Retail investors—who dominate both volumes and volatility—are exposed to excessive risk. Institutional investors, who might otherwise act as a stabilising force, are largely absent. The market’s utility as a capital-raising mechanism is compromised. Firms list not for long-term financing but to tap speculative appetites. Valuations fluctuate wildly, with little regard for profitability, sectoral performance or macroeconomic trends.
Some propose a predictable set of reforms: improve financial literacy, enhance enforcement and mandate better disclosures, among others. These are laudable, if familiar, suggestions. Implementing them means something rarer: political will and institutional capacity. The Nepal Stock Exchange is, after all, a reflection of its ecosystem: a market that has grown in breadth but not depth, where volume masks fragility.
Still, the potential for change remains. The market’s inefficiencies are not inherent, they are inherited. As household savings rise and pension funds expand, there is scope for a shift toward informed investing. Regulatory upgrades, though slow, are not inconceivable. What NEPSE lacks in maturity it compensates for in visibility: every boom and bust provides a case study, and each correction reveals a map of its excesses.
For now the index is part casino, part mood ring, part economic weathervane. Investors may speak in the language of fundamentals, but they trade in emotion. Gravity, it seems, is yet to be priced in. ■