
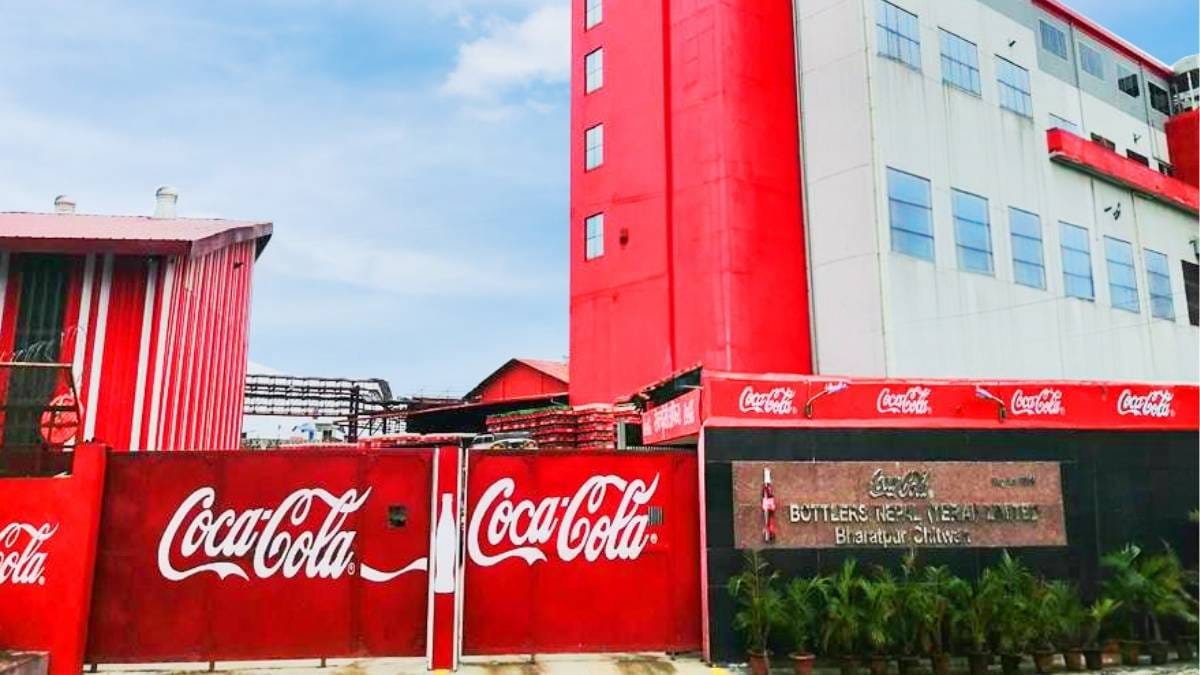
The share price of Bottlers Nepal (Terai), or BNT, one of the country’s oldest publicly traded manufacturers, is now hugging the floor. At NPR 11,545 it has sunk to its lowest level in a year, down from a high of NPR 15,410. Yet, curiously, investors still value the stock at nearly four times book. The mismatch between crumbling earnings and resilient valuations says much about the state of corporate Nepal, and of BNT itself.
BNT has for decades enjoyed a rare status on the Nepal Stock Exchange (Nepse): a company with dependable cash flows and enviable dividends. As the licensed bottler of Coca-Cola products in Nepal, it occupied a profitable niche in a protected market. From 2011 to 2025 it consistently delivered cash payouts, sometimes surpassing 50% of paid-up capital (in 2012 it hit as high as 80%). This made BNT a darling of income-seeking investors.
That equation no longer works. Last fiscal year the firm swung from profitability to severe losses. Earnings per share collapsed from a high of NPR 472 to –502, wiping out its hard-earned credibility accumulated over the years. Revenues shrank by 13% year on year; operating profit by 43%; and net profit by more than NPR 600m. Book value per share slid by nearly 16%. Worse, liabilities leapt by almost fivefold, driven by short-term borrowings to plug liquidity gaps.
The company’s woes are neither sudden nor unexplained. In fact gross margins had been narrowing, asset turnover slowing and operational costs creeping upward for several quarters. Liquidity, once comfortable, is now strained. The current ratio, a basic measure of solvency, is barely 1.0. It is no surprise BNT’s quarterly results are now awash in red ink.
What then explains the optimism priced into its shares? Perhaps a kind of selective memory. Between 2018 and 2024 BNT appeared to be staging a recovery. Revenues doubled from NPR 6.86bn to over NPR 11.2bn, and operating profit rose fourfold. Net profits bounced from losses to gains, and earnings per share turned positive. But these improvements hid underlying fragility. Margins failed to take off and return on assets began to tumble. And what growth it had was financed by expanding liabilities (rather than retained earnings).
Yet market capitalisation scaled. By early 2025 BNT was valued at over NPR 30bn, roughly five times its equity. Such valuations might be warranted in sectors driven by innovation or high growth, but BNT sells bottled beverages in a market with dismal expansion prospects and soaring costs. Compared with similar bottlers in India, BNT’s performance is subdued.
Macroeconomics helps explain why. Nepal’s manufacturing sector is beset with inefficiencies from dear energy costs to unreliable logistics and erratic policies. Industrial capacity utilisation averages under 60%, reckons an analyst at an investment firm, reflecting slack demand, especially from sectors like construction, which had been part of what drove volume for firms like BNT. Tariffs and import restrictions intended to protect local producers tend to raise input costs. And limited access to credit combined with underinvestment in technology keeps productivity low.
BNT’s peers across manufacturing from sugar and dairy to footwear are in similar straits. Even cement, a sector theoretically buoyed by public infrastructure spending, has seen profits tumble. In this environment, cash dividends take on symbolic significance: they reassure investors the company remains viable, even when profits suggest otherwise. Hence the attractiveness of its shares.
Some argue BNT’s dividend policy reflects prudent capital allocation in the absence of compelling reinvestment opportunities. Others counter it amounts to asset depletion: shareholders are being paid out of reserves rather than returns. Both positions are technically defensible. Yet both miss the bigger point: cash distributions are unsustainable in the absence of profitability. “Dividends can sugar-coat the balance sheet for a while,” says a fund manager, “but you can’t keep paying investors from reserves when earnings are bleeding.”
The company’s most recent results are a warning. While operating profits were positive, extraordinary charges (ie, “prior period tax adjustments”) reversed the gains. Investors for now seem willing to overlook this, perhaps out of habit, perhaps out of hope.
Yet should BNT continue to underperform, the share price will eventually follow fundamentals. Then that hope may prove costly. ■





