
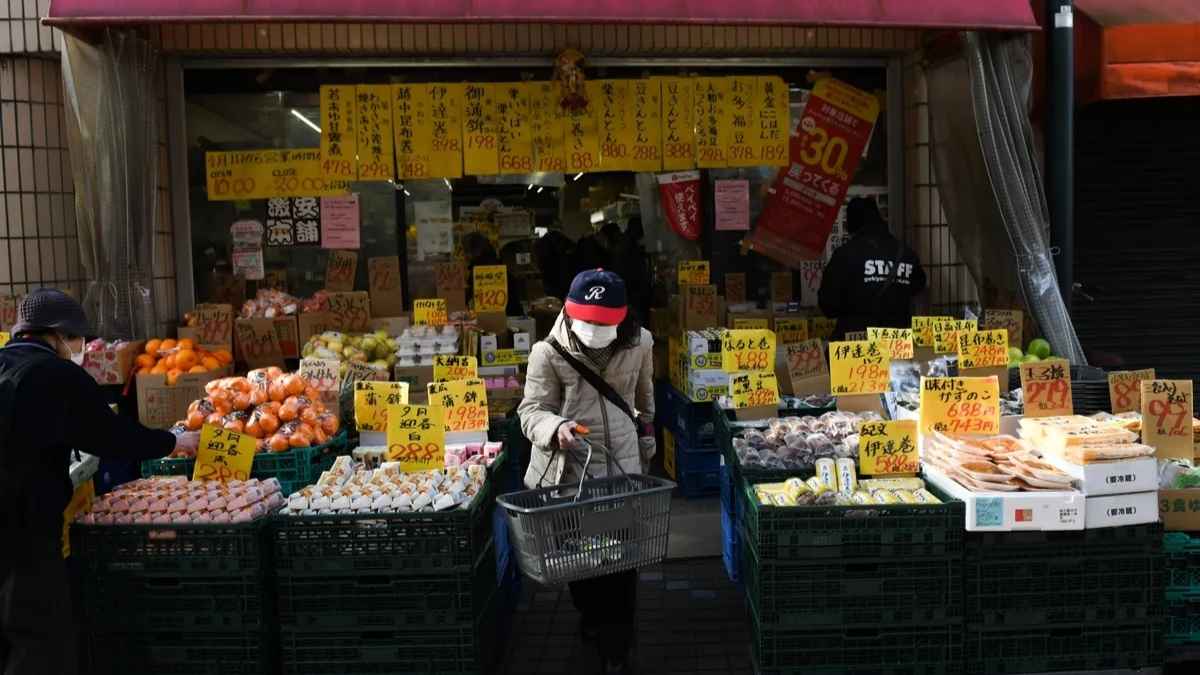
IMAGE: NORIKO HAYASHI/BLOOMBERG
EIGHT YEARS ago a Japanese ice-cream manufacturer issued a public apology. It was raising the price of a popular bar by ten yen, or about six cents, for the first time in a quarter-century, and it was profusely sorry. To most of the world, that seemed an overreaction. In Japan it was a sign of a near-sacred economic religion: the belief that prices do not, and should not, rise. That faith has now been shattered. Inflation has outstripped 3%, more than the central bank’s 2% target, and Japan recently posted the highest rate in the G7. After a 30-year fight against deflation, the return of soaring prices should be a victory. It rather feels like a perilous new chapter.
The psychology of stable prices became entrenched after Japan’s asset bubble burst in the early 1990s. What followed was, rather than a brief recession, “the lost decades”, a grinding era of falling prices, stagnant wages and feeble growth. The Bank of Japan (BOJ) responded with a radical, protracted experiment. It held interest rates at zero, then negative. It bought mountains of government bonds: the goal was to rekindle inflation, any inflation, to break the deflationary mindset. For years it failed. Salaries did not budge and neither did prices. The economy stayed in a low-pressure system where consumers delayed purchases, expecting goods to be cheaper later, and firms had no reason to invest or raise pay.
Two external shocks finally broke the spell. The pandemic and then the war in Ukraine sent global commodity prices soaring. As a country that imports nearly all its energy and much of its food, Japan was forced to import inflation. Yet the BOJ, fearing a relapse into deflation, kept monetary policy ultra-loose long after other central banks had begun tightening. That accelerated the yen’s decline, making imports even costlier. The cheap-currency policy, once a tool for boosting exports, had become a source of domestic pain.
The danger is in the nature of this inflation. It is not the healthy, demand-driven sort the BOJ spent decades pursuing. It is a cost-push inflation, driven by a weak currency and expensive imports, which squeezes households without benefiting workers. Real wages have been falling for over two years. “We have a whole generation of people who’ve never seen prices go up,” says one analyst. “This has been a terrible shock.” Small businesses are caught in a vice. They face higher costs for materials but feel intense cultural and competitive pressure against raising prices too aggressively. Many want to increase wages to help staff cope, but their margins are too slim to do so comfortably.
That presents a big political challenge for Sanae Takaichi, the prime minister. Her government has provided subsidies to blunt the cost-of-living crunch, but these are fiscally reckless stopgaps. Japan’s net public debt, at 130% of GDP, is the highest in the advanced world. The BOJ has tentatively begun raising interest rates, but moving too fast risks crashing the fragile recovery and making the debt-servicing bill explode. Moving too slowly guarantees further yen weakness and more imported inflation. It is a diabolical calibration.
The overriding fear is that Japan gets the worst of both worlds: the stagnation of its past and the instability of its present. An ageing population relies on fixed pensions that are being undercut by prices. A nascent shift of household savings into the stock market, encouraged by new tax-free accounts, could reverse if confidence falters. The political patience for the old Liberal Democratic Party is already fraying. Japan has spent a generation fearing the spectre of deflation. It has now summoned a different and just as troublesome spirit. The task is to prevent a cost-of-living crisis from congealing into a permanent cost-of-living malaise, where prices keep rising but prosperity does not. After decades of price stability, that is a dangerous and unfamiliar road. ■





