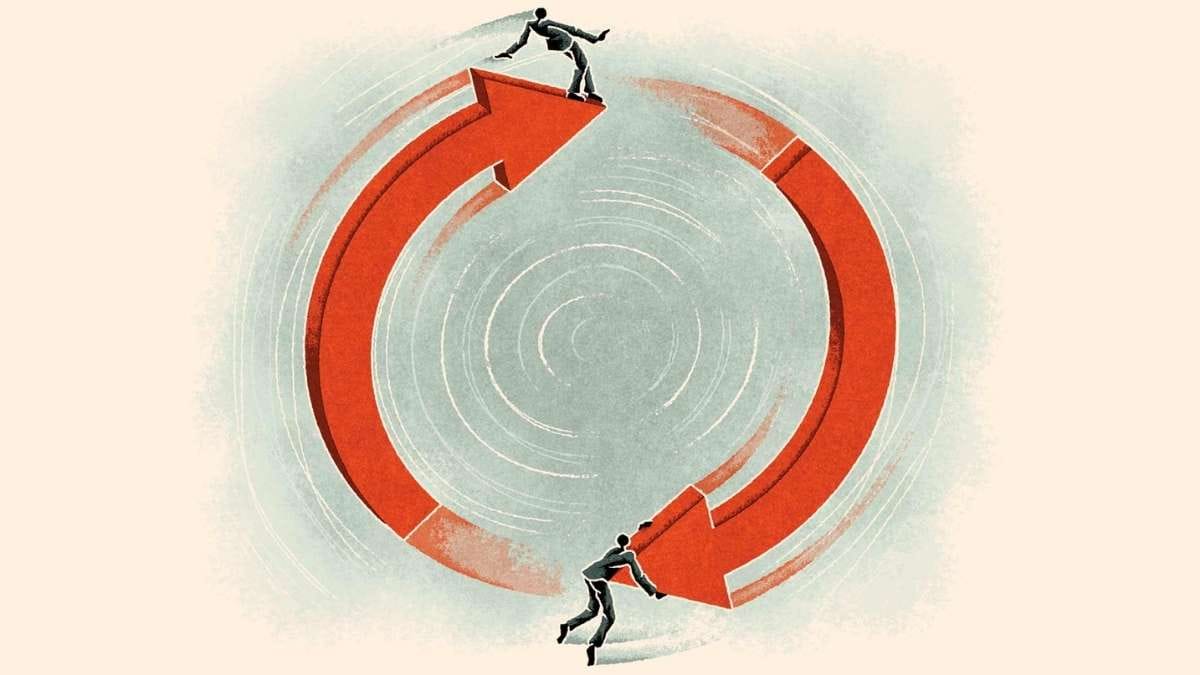
ILLUSTRATION: MATT KENYON
A COUNTRY that suffers the same financial affliction three times in three decades has either a remarkable capacity for forgetfulness or a big flaw. Nepal, it seems, has both. Since 1990 the Himalayan nation has experienced three credit booms, each preceded by financial liberalisation and loose money, each accompanied by a stockmarket frenzy, and each ending in the same painful place: a depleted currency reserve, a gaping current-account deficit and a hangover of subpar growth. The latest working paper from the Nepal Rastra Bank, its central bank, meticulously documents this sad rhythm. The question is why nobody in Kathmandu has learned to break it.
The three booms—1994-96, 2008-10 and 2020-22—share a genealogy. Financial reforms open the spigots. New banks and finance companies sprout like monsoon weeds. Cheap money, often deployed for worthy-sounding purposes like post-earthquake reconstruction or pandemic relief, sloshes through the system. Lending standards loosen. Credit surges not towards productive investment in tradable goods but towards construction, consumable loans and finance—the sectors that suffer most when the tide recedes. Stock prices double and triple; then they halve. Leverage builds; then it destroys.
That trend is hardly confined to Nepal. Credit booms are a recurring pathology of modern finance. What makes Nepal’s case more troubling is the exchange-rate peg to the Indian rupee. The peg removes the classic safety valve of currency depreciation, forcing all adjustment onto the real economy. When credit expands too fast, imports balloon, reserves shrink and the central bank must choose between defending the peg and sustaining growth. It invariably chooses the peg, as any sensible central bank with a fixed exchange rate must. Then it scrambles, with import bans and capital controls and frantic rate rises, to correct a mess it might have prevented.
The Rastra Bank’s response, detailed in the paper, shows an institution that knows what to do but cannot do it in time. In the 2008-10 boom, tightening came late. In the post-pandemic boom, the first rate rise arrived only after the stockmarket had already peaked and the current account was bleeding red. By then the damage was done. The credit-to-GDP ratio hit 95% in 2022—a dizzying figure for an economy with Nepal’s per-capita income. The subsequent deleveraging has been slow and painful, with bank assets still below their boom-time peaks.
This is not about incompetent technocrats. The Rastra Bank’s economists have produced sophisticated analysis, identified the booms with precision and recommended timely action. The failure lies elsewhere: in the political economy of booms. Loose credit is popular, especially when it inflates asset prices. Construction barons and stockmarket punters cheer. Politicians, ever attentive to the roar of the crowd, pressure the central bank to keep the party going. The Rastra Bank’s independence, formal on paper, is fragile in practice. When it finally acts, it does so with the force of a father scolding a teenager after the car has been wrecked.
The consequences are real and brutal. During the upswing credit flows to those with collateral—land and houses—which means the already well-off. During the downswing the same sectors shed workers and default on loans. Production and agriculture, the backbone of Nepal’s real economy, receive a paltry share of the credit boom. The poor gain little from the binge but suffer much from the hangover. Growth after each boom has been below trend; in 2023 real credit growth turned negative, a creditless recovery that bodes ill for investment and employment.
What should be done? The Rastra Bank can improve its toolkit and its timing. Early warning systems for credit booms already exist; they need to trigger action before the current account deficit hits 12% of GDP. Macroprudential measures—from loan-to-value limits and capital buffers to sectoral exposure caps—should be deployed pre-emptively, and not as emergency surgery. The peg to the rupee, though sacrosanct in Nepali policy circles, deserves a more honest reckoning: it constrains monetary policy and amplifies boom-bust dynamics. A managed float, or a wider band, would give the central bank more room to lean against the wind.
But technical fixes will fail without political will. Nepal’s policymakers must confront a truth they have long evaded: credit booms are dangerous, and the benefits of restraint are invisible because the crisis never happens. A central bank that acts early will be accused of killing growth; a central bank that acts late will be accused of mismanagement. The Rastra Bank will choose the latter, as central banks always do, unless its political masters give it cover to do the unpopular thing.
The paper concludes with a plea for policy co-ordination. Nepal’s credit cycle will repeat until the incentives facing politicians, bankers and borrowers change. The bankers want volume; the politicians want growth; the borrowers want cheap money. No one wants the bust.
Yet the bust arrives, like the monsoon, with predictable regularity. The Rastra Bank can forecast the weather. It cannot change the climate. Until Kathmandu accepts that financial stability requires saying no to powerful interests, Nepal will stay stuck in a cycle of ruinous credit. The next boom is already somewhere on the horizon. ■