IMAGE: NIMB
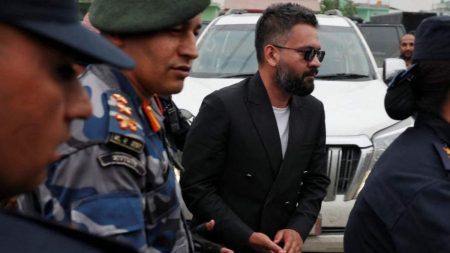
JYOTI PRAKASH Pandey did what many bankers believe they are allowed to do. When a borrower stopped paying, he moved to seize its assets and sell them. The loan to Smart Telecom, a failed Nepali mobile operator, was backed by collateral registered with the state. The auction was conducted under Section 57 of the Banks and Financial Institutions Act (BAFIA), which grants lenders special powers to enforce security interests. The price exceeded the asset’s audited book value. Then the police arrested Mr Pandey, charged him with fraud and criminal breach of trust, and took him into custody while he was traveling in Sindhuli.
Within three days the Supreme Court ordered his release, at least from custody. But the damage was done. Several banking associations protested. The Federation of Nepalese Chambers of Commerce and Industry warned that such arrests could damage business confidence and investor sentiment. And bankers across Kathmandu began asking a question that should worry anyone who lends or borrows in the developing world: if a chief executive can be locked up for exercising statutory rights that parliament explicitly granted, what is a collateral agreement actually worth?
The short answer is: not as much as the law promises. In rich countries, secured lending works because courts are predictable, title registries are reliable and police enforce contracts not grab executives. In Nepal, as in many emerging markets, collateral does not eliminate risk: it merely transforms it. Financial risk becomes legal risk (will a judge uphold your claim?), political risk (does the borrower have friends in power?) and, as Mr Pandey discovered, criminal risk (can following the rules land you in a cell?).
Consider the facts. Smart Telecom owed NIMB, Mr Pandey’s bank, more than Rs5bn ($34m). Its telecoms licence had been cancelled. The bank auctioned the assets, and Ncell bid roughly Rs4.6bn—above their audited value. Yet the police argued that once a licence is revoked, the infrastructure belongs to the state—not the borrower, and certainly not the bank. So a routine loan recovery became a clash between the banking law (which gives lenders a “first right” to auction collateral) and telecoms rules (which claim state ownership). No binding legal opinion has ever reconciled them.
That is bad enough. But the main problem is that Nepal’s entire banking system is built on institutional quicksand. Land records are incomplete, often paper‑based and vulnerable to fire or fraud, as demonstrated by the Lalita Niwas land scam. Inheritance claims can surface years after a loan is made. Borrowers commonly obtain court injunctions; civil cases can stall recovery for years, and enforcement can take an additional 180 days or more.
And when banks do seize property, they often cannot sell it: non‑banking assets (physical assets repossessed by banks) surpassed Rs50bn in early 2026, up 42% in a year. Banks are becoming the country’s largest landlords, earning nothing from assets that regulators force them to write down.
The result is a perverse feedback loop. Because enforcement is uncertain, banks demand excessive collateral—land, mainly. According to Nepal Rastra Bank data, roughly 88% of loans are backed by land or buildings. That drives up property prices, making land appear even safer, which encourages more land‑backed lending.
But when defaults rise (non‑performing loans are above 5% and climbing), banks discover that their “security” is just a claim on an illiquid asset in a slow‑moving court system. The pawnshop model of banking—bring a title deed, get a loan—has reached its limits.
What is to be done? First, clarify the law. Parliament should amend BAFIA to state explicitly that a lender’s right to auction collateral survives any regulatory cancellation of a borrower’s licence, unless the state pays compensation. No more jurisdictional whack‑a‑mole. Second, digitise land records and create a single, searchable registry. Third, expand the Debt Recovery Tribunal and restrict ex parte stay orders. Fourth, consider a “bad bank” (an asset management company) to buy and resolve the mountain of non‑banking assets—a proposal included in the 2025/26 budget, recommended by a high‑level commission chaired by Rameshore Prasad Khanal, who later became finance minister.
The alternative is a banking system that cannot perform its most basic job: turning savings into productive investment. Nepal’s banks are sitting on excess deposits while paralysed by the fear that lawful recovery could bring handcuffs. That is no way to run a financial system. Mr Pandey’s arrest was widely criticised as absurd.
Yet the greater absurdity is believing that a piece of paper—whether a title deed or a loan agreement—means anything without courts and cops that back it up. Collateral is only as strong as the institutions that stand behind it. In Nepal today that foundation is dangerously weak. ■