
IMAGE VIA FISCAL NEPAL
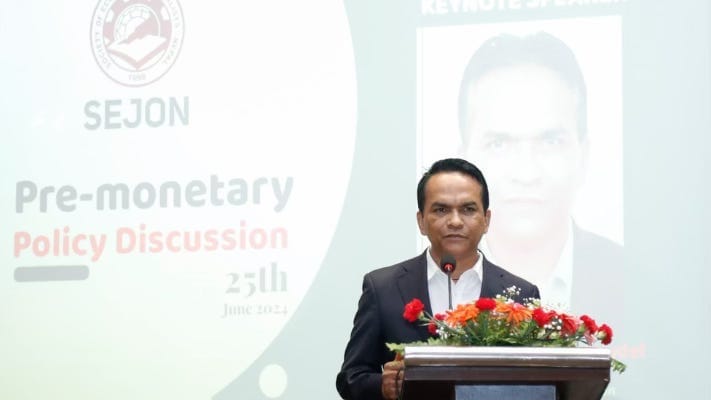
BAD DEBTS ARE like bad habits: they creep up slowly, then suddenly hit like a freight train. Nepal’s financial sector is now nursing a non-performing loan (NPL) ratio of 5.24%, the highest in living memory, with delinquencies ballooning by more than Rs95bn in just a year. That is not quite a crisis yet, but enough to make the Nepal Rastra Bank (NRB) sit up. Governor Maha Prasad Adhikari’s successor, Biswo Poudel (pictured), has dropped hints that the next monetary policy will be all about cleaning up the mess, especially loans to small businesses and farms. Trouble is, the rot is deeper than the NRB likes to admit—and looser monetary policy won’t fix it.
The damage isn’t evenly spread. Seven commercial banks, out of twenty, report NPLs well above 5%, with seized collateral stacking up. Non-banking assets—the stuff banks grab when loans sour—have jumped over 50% in a year. Earnings are throttled. Despite lower base rates than a few years ago, banks are pumping money into NRB instruments rather than productive sectors. The credit pipes are clogged.
Even bankers, usually a cautious, unflappable lot, are glum. Santosh Koirala, president of the Nepal Bankers’ Association, admits rural loan recoveries have sunk below 50%. Rajesh Upadhyay, vice-president of the Confederation of BFIs, calls the surge a “social problem”. That’s faint praise. This is economic and institutional, as well as dangerously cyclical.
The roots of the current fiasco are obvious. Covid-19 dented incomes and repayment capacity. Cooperative scandals—at least 90 firms vanished with millions—undercut trust and drained liquidity. Slow government spending as well as a cooling real estate market and import restrictions sapped revenue and slammed fiscal cushions. Into this toxic brew went the dregs of past excess: the IMF warned in 2019 that Nepal’s credit boom was unsustainable. Regulators snoozed.
The fallout: banks scrambled to set aside provisions; capital buffers weakened; and lending ground to a crawl. SMEs and farms, the sectors the government likes to champion, were the first to choke.
Nepal has danced this dance before. In the late 1990s state-owned banks went haywire: Rastriya Banijya Bank’s NPLs shot from 20% in 1998 to a stonking 60% by 2003. Cleaning up cost Rs3.5bn—half the national budget at the time, 9% of GDP. Reforms backed by the World Bank and the IMF restored order, but at a punishing fiscal price.
Elsewhere, countries have faced worse—and bounced back. After the 1997 Asian financial crisis, Indonesia, Japan, South Korea and Malaysia all set up government-backed asset management companies (AMCs) to wrestle bad debts and revive balance sheets. Indonesia’s IBRA, Japan’s RCC and IRCJ, South Korea’s KAMCO: they all recovered chunks of toxic assets. Malaysia’s Danaharta sorted loans by size and recoverability, pulling back nearly 60% of value. Japan did even better: recovery rates hit 104% thanks to strict case-by-case resolutions and competent execution.
The takeaway: balance-sheet clean-ups demand more than stern warnings and tweaks to base rates, meaning they need institutional muscle. The NRB, for all its tools, cannot perform surgery on festering assets. A well-crafted AMC could act as a financial firebreak, letting banks shed bad loans and get back to lending. But structure matters: if AMCs simply mop up debts without punishing reckless lenders, moral hazard thrives. Banks will keep lending carelessly, knowing someone else will foot the bill.
To avoid that trap, any AMC must have teeth: punitive pricing as well as loss-sharing and strict eligibility filters. It must be insulated from political meddling—a tall order but not impossible. Strong governance, perhaps with international oversight, would help preserve credibility.
The NPL ratio might look tolerable by global standards. Yet in a slimly capitalised banking system with limited fiscal room, even small shocks cascade. Left unchecked, bad debts will sap investor confidence and crowd out productive credit. Worse, it will weigh down an anaemic economy. They may even freeze lending altogether, starving SMEs, the backbone of the economy, when they need cash most.
The NRB is right to worry. But worry alone won’t stop the slide. Monetary policy can tighten or loosen credit. It cannot excise toxic loans. That needs an institutional scalpel. A properly designed AMC would be a start. As Japanese banking reformers discovered, fixing a broken system means learning to live with its scars—and making sure they never reopen. ■





