
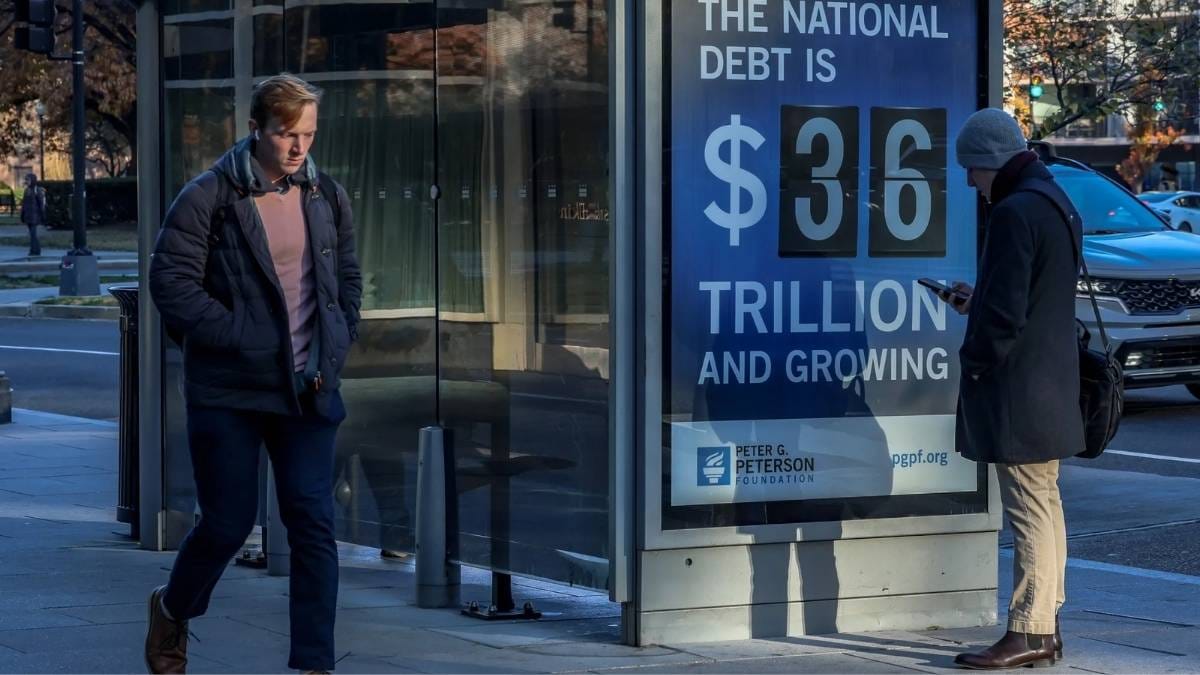
Photographer: Jemal Countess/Getty Images North America
THE FISCAL deficits speak volumes, though few in power seem inclined to listen. Across the rich world, sovereign debt ratios have returned to the vertiginous heights last seen in 1945—when the war that caused them at least had a clear purpose. Now the build-up reflects something murkier: a political addiction to debt, paired with a disinclination to pay for public spending in real time. The fallout is a growing worry among bondholders that the global economy is drifting towards a reckoning. No one knows exactly where the tipping point lies. But confidence in the market’s infinite tolerance for deficits is beginning to wear thin.
The numbers are terrifying. The average public debt-to-GDP ratio in advanced economies is around 100%. In America, the world’s benchmark borrower, the deficit is running at roughly 5.6% of GDP, remarkable in a time of full employment and no declared emergency. Japan’s debt load has surpassed 250% of output, Italy’s hovers near 140%. France, Canada and the UK are not far behind. For now bond markets continue to absorb the deluge of issuance. But investors are becoming more discerning, and episodes of indigestion are appearing more frequently.
Governments have arrived at this juncture through a series of shocks—financial crisis, pandemic, war—and a set of political incentives that reward short-term largesse. The logic has been this: when trouble strikes, spend liberally. The cumulative effect, however, has been to entrench structural deficits. More alarmingly, it has nurtured an expectation that borrowing can proceed indefinitely without consequence.
The story has unfolded differently across countries, though the chorus is broadly the same. In the eurozone, Italy’s debt pile has long been viewed as the bloc’s weak link, but France’s fiscal indiscipline increasingly draws scrutiny. Germany, the avatar of budgetary rectitude, has begun to edge towards more expansive spending, spurred by sluggish growth and defence needs. Britain, meanwhile, received a sharp reminder of bond market discipline in 2022 when the Truss government’s fiscal adventurism provoked a gilt market rout that required emergency intervention from the Bank of England.
Then there is America. Its economy anchors the global financial system. Its Treasury bonds serve as the world’s reserve asset. And its fiscal outlook is—by most conventional standards—deteriorating. Interest payments now outstrip military spending, and projections show debt reaching 160% of GDP (versus 120% now) within a decade. Still, bipartisan consensus on deficit reduction seems elusive. Meanwhile Donald Trump has cut taxes and boosted spending.
The standard defence is governments borrowing in their own currency cannot default, at least not involuntarily. That is true, but not particularly reassuring. Inflation provides a theoretical escape route, eroding debt burdens over time. Yet for that strategy to work, inflation must exceed expectations without triggering a sell-off in bonds. In practice that combination is difficult to engineer, and possibly destabilising. The 1970s offer a vivid reminder of what happens when inflation runs ahead of monetary credibility. Investors, burned once, may not be so forgiving again.
Some argue debt fears are misplaced: that fiscal deficits are merely the flipside of private sector surpluses, and that higher public borrowing simply reflects demand for safe assets. That framing has intellectual merit but limited political traction. Voters do not think in terms of sectoral balances. They notice rising mortgage rates and crowding out of public investment, as well as politicians unable to keep fiscal promises.
Others point to Japan as evidence high debt can be managed indefinitely. But Japan is the exception that proves the rule. Its bond market is domestically held; its central bank is trusted; and its population tolerates stagnation in a way that few Western electorates would. Importing that model would mean more than policy tweaks: it would mean a wholesale remaking of expectations around growth, inflation plus the role of the state.
Austerity at scale is politically improbable. Inflation, if revived too vigorously, is politically intolerable. That leaves technocratic tinkering and slow adjustments as the most viable path. Some governments will seek to “financially repress” savers: nudging institutions to hold more government debt; tolerating negative real returns; and keeping central banks on a tight leash. Others may attempt modest consolidation under the cover of fiscal rules. But the room for manoeuvre is narrowing.
The bond vigilantes—the once-feared enforcers of market discipline—have been in retreat for two decades. Yet their reappearance, if it comes, would not be gradual. The lesson from the Truss episode is that markets tolerate deficit financing, until they do not. And when that patience runs out, the response can be fast and punishing.
Governments, for the most part, are confident they will muddle through. Perhaps they will. Financial markets are resilient, and political systems adapt, eventually. But the longer the debt cycle stretches, the greater the risk that adjustment arrives through crisis. That would amount to a repudiation of the very promise government debt was meant to uphold: security. ■





